Wednesday, November 1, 2017

Target Investment Plan

TIP is an innovative additional to mutual fund scheme. It is like a SIP i.e. investing opportunity for a determined period on a regular basis with a set target. TIP helps you to invest with target set plan and time period. Financial goals like buying a house, car or educations of child, can be achieved through this TIP.
TIP key principle is that “TIP invests less when prices are high and invest more when prices are low” which helps in averaging the investment value. The longer the period of investment the better is the opportunity of achieving the target.
Some of the key features of TIP are:
  • Plan goal to be achieved, its target amount and its time period.
  • Set an average monthly investment amount details and additionally offers for providing a maximum amount.
  • Investing more when prices are low and investing less when prices are high.
  • TIP often tends to give more returns as compared to SIP (SYSTEMATIC INVESTMENT PLAN).
Suppose you have a house to buy after 7 years assuming its fees to be paid is Rs 1cr, you can start your target amount as Rs 1cr.
TIP Dates Opening Portfolio RS Monthly Installment Rs Closing Portfolio Rs Remarks
7th June 2017 0 77,000 77,000 This is the first installment.
7th July 2017 70,000 84,000 154,000 Portfolio Value went down hence the monthly installment went up.
7th August 2017 170,000 61,000 231,000 Portfolio value went up hence the monthly installment went down.
7th September 2017 220,000 88,000 308,000 Portfolio Value went down hence the monthly installment went up.
7th October 2017 320,000 65,000 385,000 Portfolio Value went up hence the monthly installment went down.
One can cap their maximum installment in TIP. The first investment amount will be equal to average amount of investment.
Thus TIP establishes target portfolio value by calculating the investment amount periodically and bridging the gap between target value and actual value.

  Click Here to invest.

Thursday, October 26, 2017

Knowing Your Mutual Fund Product Better!

When a mutual fund creates an investment product, it offers it for the first time to the investors as a new fund offer (NFO).  A new product is first approved by the trustees, and features are described in a detailed offer document that is filed with SEBI.  After SEBI approves that the document carries all the necessary disclosures in the interest of investors, the mutual fund makes its new fund offer to investors.  Key information about the products is also made available to investors who like to buy units of an open‐ended fund on an on‐going basis. SEBI’s regulation prescribes that information about the fund and the product be disclosed in two sections ‐ Scheme Information Document (SID) and Statement of Additional Information (SAI).  The regulations define specifically all the information that needs to be provided and the format in which this information has to be provided.
The SID contains information that is relevant to a specific mutual fund scheme. Information in the SID includes the type of the scheme, its investment objectives, maximum and minimum allocation to different types of securities, the risks associated with the scheme and the strategies that the fund manager intends to deploy. The fees, expenses and loads that will be charged to the scheme are also given. The document gives details on the operational features such as, such as dividend and growth options and facilities such as switch and systematic investments. The SID also contains information on the price at which the units are being offered, the dates of opening and closing of the NFO, the minimum application amount and the points of acceptance of the application. For investors in the scheme after the NFO, the SID contains information on the past performance of the scheme, the method for calculating the price for purchases and redemptions, the cut‐off time within which the application has to be submitted and the minimum application amount.
The SAI contains information that is common to all schemes of a fund house. This includes information on the constitution of the mutual fund, the details of the constituents such as the trustees and the AMC and their roles and responsibilities. Information on service providers such as the custodian and R&T agent and their contact details are provided. The rights of the unit holders in the mutual fund are mentioned in the document. Information contained in the SID or the SAI may change. Changes in the fundamental attributes of the scheme, such as the type of the scheme or the investment objective, has to be updated in the SID immediately. In case of other changes, the mutual fund will issue an addendum which will be attached to the existing SID. Material changes in the SAI will be updated and uploaded both on the mutual fund and AMFI’s website. The SID and the SAI will be updated once every year and the information in the addendums will be incorporated into the document.
A condensed version of the SID and the SAI called the Key Information Memorandum (KIM) is attached to every application form. It gives brief details about the scheme and its features, loads and expenses that will be charged to the investor and the past performance of the scheme. Investors who require information in greater detail can ask for the SID and SAI. Correct, relevant and timely information is essential for investors to make the right investment decisions. Mutual funds provide the information in a simple and readily available form for investors to access and use.

Tuesday, October 24, 2017

Importance of Mutual funds in Financial Planning

Few years ago, manufacturers of ready‐to‐eat Indian food were baffled with the poor response to their range of convenience foods.  Beyond young single people, the market refused to expand to families. Their research showed that families were looking at saving time spent in the kitchen.  What was going wrong?  Another research was commissioned, which showed that the woman of the household preferred to add her ‘touch’ however little it may be, before serving the meal. The market for gravies and mixes thus took off.   In managing our finances, several households tend to choose the do‐it‐yourself path, to their disadvantage. There may be a high in whipping up an exotic investment recipe for our households.  But it suffers the same risks that an amateur cook will bring, simply because the off‐the‐shelf solution did not appeal to the ego.
We can take a better approach.  We know our nutrition needs and design meals that cater to the specific needs of the family.  We can exercise our choices in bringing the meal to the table.  We could similarly take hold of the planning of our finances and our specific needs and use pre‐designed portfolios to meet those needs.  Mutual funds offer their portfolio management skills to help households build their portfolios, so that the family’s financial well‐being can be taken care of.  The job of choosing the product and deciding what works for us is still ours on which we could focus.
Financial planning is about taking charge of the long term well‐being of the family.  If we think our child needs a glass of milk a day, we do not indulge in nurturing a cowshed but buy packed milk off the shelves.  If the child needs funding for education and we know this means a large sum of money sometime into the future, we can choose to buy an equity fund that gives us long term growth.  If we think our nutritional needs change as we age, we can buy oats off the shelf.  We make that decision to switch to the oats instead of the craving for the parantha.   But we still pick that oats pack off the super market’s shelves.
 Mutual funds represent that range of pre‐packed products that enable us to implement our financial plans.  What they are made of and how they would contribute to our financial health is pre‐defined.  An equity fund will focus on growth and carry long term benefits and short term risk.  Our decision should be about how much of equity we need to have, given our need.  Just as we decide how many rotis the teenage son will eat, compared to his grandpa. Having made that decision, we buy a well-managed equity fund, rather than wasting our energies in creating an equity portfolio, share by share, on our own.  Mutual funds enable us to focus on our core planning needs, without frittering away our time doing elaborate chores that can be efficiently outsourced.

  Click Here to invest.

Monday, October 16, 2017

Financial Goal Based Investing

When we take our family on a holiday, we make several plans – for travel, stay, sightseeing, equipment, food, and other expenses.   Many of these decisions however depend on a crucial factor – our travel destination.  If we travel to Ladakh we will carry woolens and trekking equipment; if we went to Goa we will pack sun screens and swimming costumes.   Our travel plan is defined by the destination.  Similarly, our investments have to be defined by our financial goals.
We may have a long list of things we like our savings to achieve.  Educating our children, getting them married, planning for a comfortable retired life, owning a home, re‐doing our existing homes, funding our holidays, and so on.  These large ticket items that cannot be met with our regular income require us to set money aside.  But saving alone may not be enough ‐ we need to plan about how to invest those savings, so that we are able to meet the goal we have in mind.  Such an approach is called financial goal‐ based investing, and is a useful way to plan and provide for several critical large expenses that we have to incur.
Consider for example, the education of the children.  We may begin to set aside some money for them when they are young.  But choosing an investment plan requires an understanding of three things.  First, we define the goal in terms of amount of money and time.  Assume that we like to save for the child to pursue a professional course, after 16 years.  We know that it costs, say, Rs.1 lakh a year today.  We need to consider the effect of inflation on this goal. Assume we estimate an inflation of 6%.  That is the minimum rate of return our investment must make, so that the amount grows at least to cover the effect of inflation.  Second, we need to understand how much we can save per year for this goal.  This depends on our income and expense patterns and our seriousness about this goal. Third, we have to choose an investment option that generates enough return to meet the goal.
We either increase the savings or we choose a higher return yielding investment, and balance the two.   Too high savings may be impractical; too high an investment return may be risky.  We therefore have to consider the time on hand.  Longer the time we have, greater is our ability to choose higher return and higher risk investments. If the return on our investment is high, the same goal can be met with lower amount of saving, freeing money for other goals.   A slow train will be less expensive, but take us time to reach.  A flight will reach us to the same place faster but costs more.  We have to make the same choice with our investments, based on the time we have.
Mutual funds aims to fund our financial goals by offering a range of products that help us earn income or achieve growth over a long period of time.   Goals give our investments a purpose and make it easier to choose our investment vehicles.
 NOT A MEMBER YET? REGISTER HERE TO BUY MUTUAL FUND ONLINE- http://wavesmf.com/buy-online-nse-login/

Thursday, September 21, 2017

Right Timing for Investing in Mutual Fund

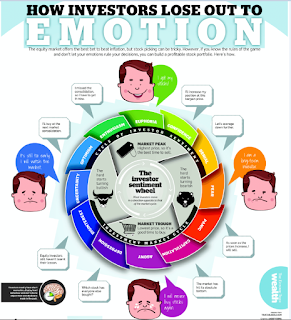
If you are an investor, and thinking to invest in equity market only because the market is down, I would suggest it’s a wrong choose. Whereas, taking out the investment from the selloff market can be considered as the wrong thought.
One needs to understand that Mutual fund is a financial tool where investors can invest for  long term perspective to have a wealth gain. If you follow financial discipline, then there is no one to stop you to make handsome profits.
But the frequent question arises by people is, what can be the best time to invest in Mutual funds? The answer is, “Invest when you have money, rather than when market is down.”
Also the main consent of people is when to sell or redeem the units. The selling or redemption part should not be done on the down market situation or the good market situation. It’s like whenever you need money sell the units.
There should be future objectives behind every investment. It is very difficult to know whether the market situation indicate to buy or sell. As market is unpredictable in nature. If you have planned to invest in Mutual fund for more than 5 years than you should start investing in systematic investment plan (SIP) scheme.
SIP is the schemes were investor can invest a fixed amount on monthly bases. This can even help investor to generate saving habit. SIP allows buying units on a given date of each month. SIP is generally preferred for equity funds.
SIP’s are always beneficial for the investor just because when the market is up, scheme makes money and if the market is down you make even more. After investing in such a long term scheme, one can make around 12-15% return annually.
Continue investing with the set future objective and when the time is nearer to goal, take out all your investment from equity fund and invest all in debt fund.
Some people have lump sum of amount to invest but they waste time in just thinking whether to invest today or afterwards. They think the stock price will collapse. But the fact is, one who waits will wait.
So it’s the right time to dive into SIP scheme. Click Here to invest.

Thursday, September 14, 2017

Compounding: Eighth Wonder of the World!!!

Saving money regularly and investing them into relatively safer financial instruments yielding moderate returns can work wonders over long period of time. Also Napoleon Hill the author of Think and Grow Rich says, “Make your money work so hard for you that you do not have to work for it.”

The power of compounding is such that it helps you to reach your financial goals. Compound growth refers to earning returns on your returns or similarly, earning interest on interest.

The power of compounding is very beneficial to long term investors.


Mutual Funds were made to make investing easy, so investors do not have to be burdened with picking the individual Stocks. When it comes to Compounding, do not trust your intuition, you have no idea how powerful it is.

Wealth cannot be created overnight it needs to be nurtured with care. Compounding teaches that we do not have to invest huge but regular savings can increase your wealth. As it is rightly said, “Little Drops of Water Make the Mighty Ocean.”

One can make regular savings by investing in SIP as it is very convenient mode of investment and it supports the power of compounding very well.


Click HERE for more details.

Wednesday, August 23, 2017